
Update, 21 October 2026: This analysis was written in November 2025; its prices, figures and outlook are as of that date. On 3 November 2026 the gold Ask was $3,965 an ounce and silver $49.77, 27% and 58% below the records both set on 29 January 2026. For the record and the crash that followed, see gold price in 2026. Wondering whether Chase or another bank sells gold bullion? See can you buy gold from a bank.
When the world’s largest banks begin issuing blockchain-based tokens representing dollar deposits, it signals more than just technological innovation, it reveals fundamental weaknesses in the existing financial system. JP Morgan’s JPM Coin deposit token, now operating through their Kinexys platform, represents a significant step toward digitizing traditional banking. However, this development simultaneously highlights why physical gold remains irreplaceable as a wealth preservation asset in an increasingly digitized financial landscape.
Understanding the distinction between tokenized banking products and physical precious metals has never been more critical for investors navigating 2025’s complex market environment. As gold reaches new all-time highs above $4,000 per ounce and banks accelerate their blockchain initiatives, the contrast between centralized digital tokens and decentralized physical assets grows increasingly apparent.
What Is JPM Coin and Why Does It Matter?
JP Morgan’s JPM Coin functions as what the bank calls a “deposit token”, a blockchain-based representation of U.S. dollar deposits held at JPMorgan Chase Bank. Unlike cryptocurrencies or stablecoins, JPM Coin represents a direct liability of the bank itself. According to JPMorgan’s official documentation, the token enables near-real-time payments 24/7 among approved institutional clients.
The system has processed over $1.5 trillion in transaction volume since inception, with average daily volumes exceeding $2 billion. These impressive figures demonstrate genuine institutional adoption of blockchain technology for traditional banking functions.
The Architecture of Digital Banking Control
JPM Coin operates on JPMorgan’s proprietary Kinexys platform (formerly called Onyx), a permissioned blockchain network. This architecture reveals the fundamental nature of the system: it moves money faster, operates around the clock, and leverages blockchain technology, but it remains entirely controlled by the issuing bank.
When you hold JPM Coin, you don’t hold currency. You hold a tokenized claim on deposits at JP Morgan. The distinction matters profoundly: if the bank faces difficulties, your digital token faces the same counterparty risk as traditional deposits, despite the technological sophistication of its delivery mechanism.
This represents what many observers call “centralized digitization”, making the existing system faster and more efficient while retaining all the structural dependencies and systemic risks that characterize traditional banking.
The Tokenization Trend: Banks Modernizing Legacy Infrastructure
JPM Coin represents just one example of a broader trend toward tokenizing traditional financial assets. Major financial institutions globally are exploring similar initiatives, recognizing that blockchain technology offers significant operational efficiencies for clearing, settlement, and cross-border payments.
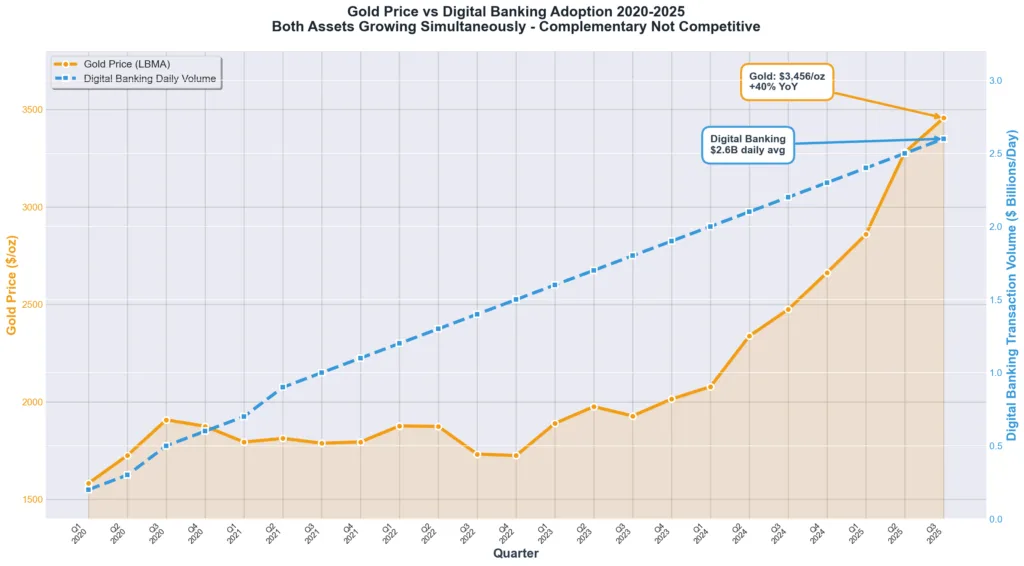
World Gold Council data from Q3 2025 shows that while financial innovation accelerates, gold demand simultaneously reached record levels, 1,313 tonnes in Q3 alone, valued at $146 billion. This parallel trend suggests investors view digital banking innovation and physical gold ownership as complementary rather than competitive strategies.
The Paradox of Digital Gold Tokens
Attempts to tokenize gold itself reveal the limitations inherent in digitizing physical assets. Paxos Gold (PAXG), one of the most established tokenized gold products, offers each token backed by one fine troy ounce of LBMA-certified gold stored in London vaults. The product works well for specific use cases requiring quick settlement or fractional ownership.
However, tokenized gold fundamentally transforms the nature of gold ownership. You no longer hold physical metal, you hold a digital claim to metal held by a custodian. This introduces several layers of dependency:
- Custodial risk: Your claim depends on the custodian maintaining proper storage and records
- Platform risk: The blockchain platform must remain operational and accessible
- Redemption risk: Converting tokens back to physical metal involves procedures, fees, and potential delays
- Regulatory risk: Changes in regulations could affect your ability to access or transfer tokens
As the saying goes among precious metals advocates: “If you don’t hold it, you don’t own it.” Tokenization, regardless of how sophisticated, creates a separation between the holder and the physical asset.
Why Physical Gold Offers Unique Advantages
Supporters of physical gold argue that its case rests not on rejecting digital innovation but on what different assets do. They point to characteristics that tokenized or digital alternatives do not replicate.
Final Settlement Outside the System
Physical gold held in your possession or in allocated storage under your control represents final settlement. There’s no counterparty standing between you and your asset. No bank needs to remain solvent, no blockchain needs to operate, no custodian needs to maintain records. The metal simply exists, holding value regardless of institutional continuity.
In past crises, some claims and contracts have failed while physical assets stayed in their owners’ hands. Our analysis of gold’s behavior during liquidity crises sets out the argument that physical metal works as insurance against system failure, although gold’s price can still fall during a crisis, as it did in March 2020.
24/7 Accessibility Without Intermediaries
While JPM Coin offers 24/7 operation, it requires the bank’s systems to remain functional and your account to remain in good standing. Physical gold requires no such dependencies. It remains accessible regardless of:
- Banking hours or system maintenance
- Account freezes or restrictions
- Payment network disruptions
- Geopolitical restrictions on cross-border transfers
- Changes in terms of service or fee structures
U.S. household debt reached a record $18.59 trillion in the third quarter of 2025, according to the Federal Reserve Bank of New York. Supporters of physical gold argue that when leverage is high across the economy, an asset that does not depend on any institution’s solvency or on credit availability adds a kind of protection that deposits and tokens do not.
Inflation and Currency Debasement Hedge
Digital dollar tokens, whether issued by JP Morgan or other institutions, remain denominated in and redeemable for U.S. dollars. They may move faster and settle more efficiently, but they offer zero protection against dollar devaluation or monetary expansion.
Gold is not a claim on any currency, and over long periods it has broadly kept pace with inflation, though with long stretches of losses in real terms, such as the two decades after its 1980 peak. With central banks purchasing 634 tonnes year-to-date in 2025 and the gold price at records above $4,000 per ounce, official buyers were clearly treating gold as a reserve asset.
Privacy and Financial Autonomy
Blockchain-based banking tokens, operating on permissioned networks, create perfect transaction records. Every movement of JPM Coin gets recorded, tracked, and potentially monitored. For legitimate commercial purposes, this transparency offers benefits. However, it also represents total surveillance of financial activity.
Physical gold held in direct possession does not create a ledger entry for every later movement. Dealers still verify identity and report certain transactions (for example, cash payments over $10,000 on IRS Form 8300), and selling gold at a profit can be taxable.
As programmable currencies and central bank digital currencies (CBDCs) advance, some savers say they value holding part of their wealth in a form that cannot be programmed or frozen remotely.
The Irony: Banks Building Digital Rails While Holding Physical Metal
Perhaps the most revealing aspect of bank tokenization initiatives is what financial institutions do with their own balance sheets. While JP Morgan pioneers digital dollar tokens for client use, major banks maintain significant involvement in physical precious metals markets.
JPMorgan serves as an approved vault operator for COMEX gold and silver, storing thousands of tonnes of physical metal backing futures contracts. Some observers read this combination, digital deposit tokens on one side and a physical metals vault on the other, as a sign that large banks see a lasting role for physical metal alongside digital money.
The AI job displacement trends affecting 2025 labor markets add another dimension to this analysis. Some analysts argue that as technological change and economic uncertainty increase, assets outside the digital system become more appealing to some savers.
Central Banks Choose Physical Over Digital
Supporters of physical gold often point to central banks. These institutions have access to every form of financial technology and synthetic exposure, yet the gold in their reserves is overwhelmingly physical metal.
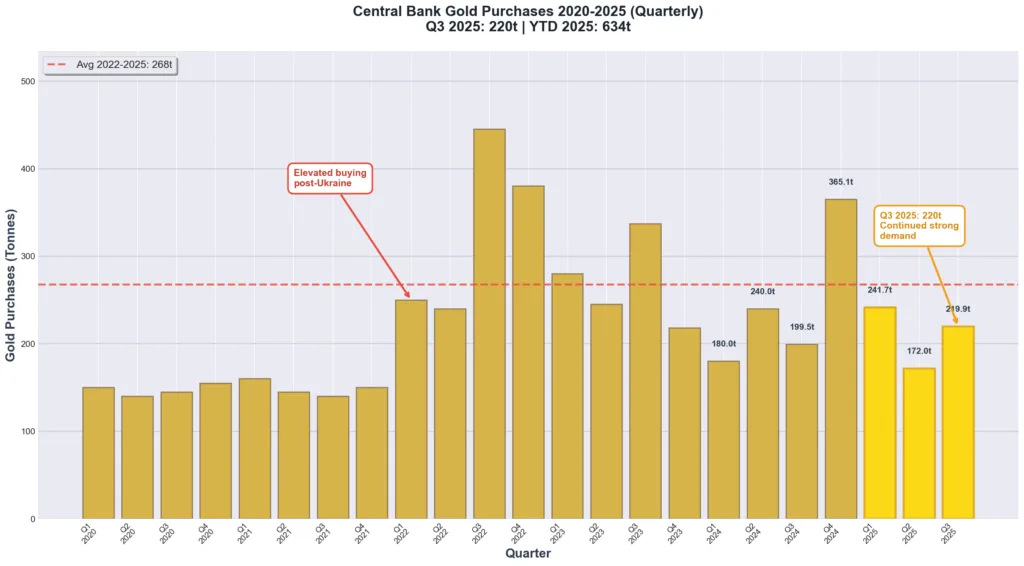
According to World Gold Council Q3 2025 data, central banks purchased 220 tonnes in Q3 alone, maintaining elevated buying for the fourth consecutive quarter. Year-to-date purchases of 634 tonnes continue a multi-year trend of aggressive accumulation.
Central banks could hold gold exposure through derivatives, ETFs or tokenized products. Reasons given for holding physical metal instead include:
- No counterparty risk
- Final settlement asset in international reserves
- A long history as a store of value across regimes and crises
- Liquidity independent of financial system operation
- Political neutrality and universal acceptance
Their choice does not settle the question for individual savers, whose needs, costs and time frames differ, but it shows how official reserve managers weigh the options.
Investment Demand Drives Gold to New Records
While banks build digital infrastructure, investors have pushed gold to unprecedented price levels. The LBMA gold price averaged $3,456.54 per ounce in Q3 2025, up 40% year-over-year, and has since exceeded $4,000 per ounce in November 2025.
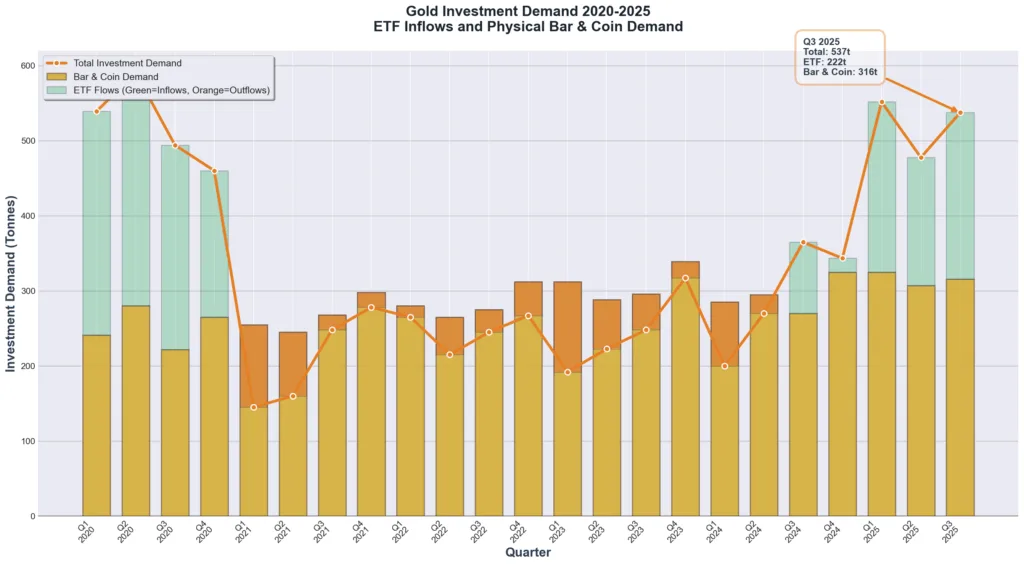
This price appreciation occurred alongside massive investment flows. Gold-backed ETFs saw inflows of 222 tonnes in Q3 2025 alone, while bar and coin demand remained above 300 tonnes for the fourth consecutive quarter at 316 tonnes.
The structural bull market in gold reflects multiple converging factors that digital tokens don’t address:
- Persistent inflation concerns despite central bank tightening
- Geopolitical tensions and de-dollarization trends
- Fiscal unsustainability and sovereign debt concerns
- Banking system fragility revealed by regional bank failures
- Currency debasement through continued monetary expansion
The Roles Investors Assign to Gold
The usual case made for physical gold doesn’t rest on competing with or replacing digital banking innovations. Investors who hold it typically cite these roles:
- Systemic insurance: an asset that does not depend on the financial system
- Currency debasement hedge: a store of value outside any one currency
- Diversification: Low correlation with traditional financial assets
- Long-term wealth preservation: an asset that can be held across generations
Digital banking tokens do a different job: daily transactions and short-term settlement. As claims on a bank, they carry that bank’s risk when the financial system comes under pressure.
What Tokenization Changes
There’s a fundamental philosophical point underlying the physical gold versus tokenized asset debate: some things don’t improve through digitization because their value lies precisely in existing outside digital systems.
Gold has served as money and wealth storage for over 5,000 years without requiring upgrades, protocols, or technical infrastructure. This is a feature, not a bug. Attempts to “improve” gold through tokenization add efficiency for certain use cases while eliminating the core characteristics that make gold valuable in the first place.
It’s similar to claiming that scanning the Mona Lisa and creating an NFT “improves” the painting. You may have created a more tradeable, more divisible digital asset, but you haven’t improved the original, you’ve created something different that serves different purposes.
The Question of Use Case
This analysis doesn’t suggest tokenized assets or digital banking innovations lack value. They solve real problems around payment efficiency, settlement speed, and operational costs. For international corporate treasury management or high-frequency trading operations, JPM Coin-type solutions offer genuine advantages.
For long-term saving and protection against systemic risk, supporters of physical gold argue that it offers characteristics digital alternatives cannot replicate. The two serve different purposes and aren’t directly competitive.
Looking Ahead: Digital Innovation and Physical Assets
The future likely includes both accelerating digital innovation in financial services and sustained demand for physical precious metals. These trends complement rather than compete with each other.
As central bank digital currencies (CBDCs) advance, programmable money becomes technically feasible, and financial surveillance capabilities expand, the attributes of physical gold, privacy, autonomy, final settlement outside the system, may become more valuable rather than less.
Similarly, as AI-driven economic disruption creates uncertainty about future employment patterns and income distribution, some investors look for assets that do not depend on the credit system.
Conclusion: Different Tools for Different Jobs
JP Morgan’s success with JPM Coin demonstrates that blockchain technology offers genuine value for improving traditional banking operations. The platform’s $1.5 trillion in transaction volume proves that institutional clients benefit from faster settlement, 24/7 operation, and improved efficiency.
Supporters of physical gold argue that this achievement does not weaken their case. Digital banking tokens, regardless of their sophistication, remain claims on fiat currency maintained by centralized institutions. They make the existing system more efficient without addressing fundamental concerns about currency debasement, counterparty risk, or systemic fragility.
Physical gold offers a different set of characteristics: final settlement, no counterparty risk when held directly, independence from any institution, and a history as money and a store of value going back thousands of years. Its supporters argue these matter more as financial systems grow more complex and digitally dependent. Its price, however, can be volatile.
The record gold demand in Q3 2025, with 1,313 tonnes valued at $146 billion, showed strong interest in gold at the time, and central banks kept adding physical metal despite having access to every form of synthetic exposure.
The choice is not necessarily between digital innovation and physical assets: they do different jobs. Deposit tokens make bank money faster to move; physical gold is an asset outside the banking system, with its own costs (dealer spreads, storage, insurance) and price risk.
Bullion Trading LLC sells gold, silver, platinum and palladium coins and bars, from small coins to kilo bars, online and at its store on New York’s 47th Street. This article is not investment advice.